Financial Intelligence for Achievement of Financial Freedom.
Global Interest Rates:
- The yield on the US 10-year Treasury bond remains near 5%, reflecting investor caution ahead of next week’s Federal Reserve policy meeting. Markets are pricing in an approximately 90% probability that the Fed will leave interest rates unchanged, but the odds of a 25-basis-point rate hike in December have risen to around 76%.
- Economists increasingly expect the European Central Bank (ECB) to raise interest rates by a further 0.25 percentage points in December 2026, taking its deposit rate from 2.50% to 2.75%, before potentially maintaining that level for an extended period. The outlook reflects persistent inflation, elevated energy prices and uncertainty surrounding the economic consequences of geopolitical tensions. A Reuters poll published on 8 October found that 64 of 73 economists surveyed expected a December increase.
- In contrast, South Africa’s inflation outlook has shown encouraging signs. The latest inflation reading came in below market expectations, strengthening the case for the South African Reserve Bank’s Monetary Policy Committee (MPC) to leave interest rates unchanged at its final meeting of the year. A pause in the rate-hiking cycle would provide much-needed relief for households and businesses facing elevated borrowing costs.
SA Company News:
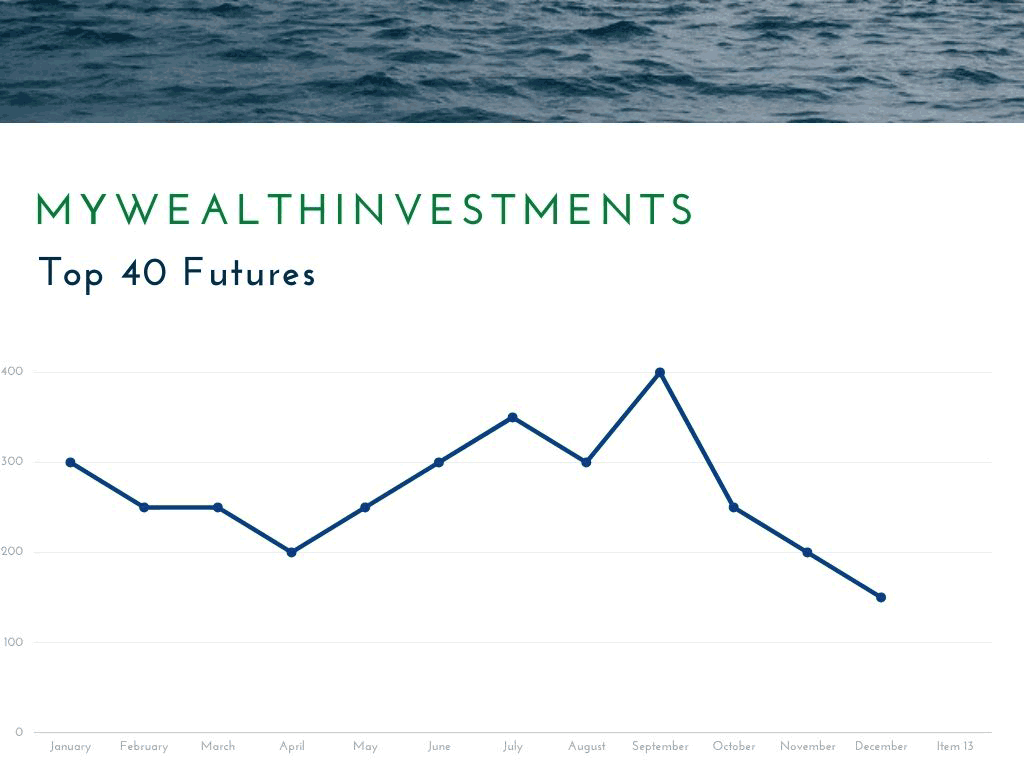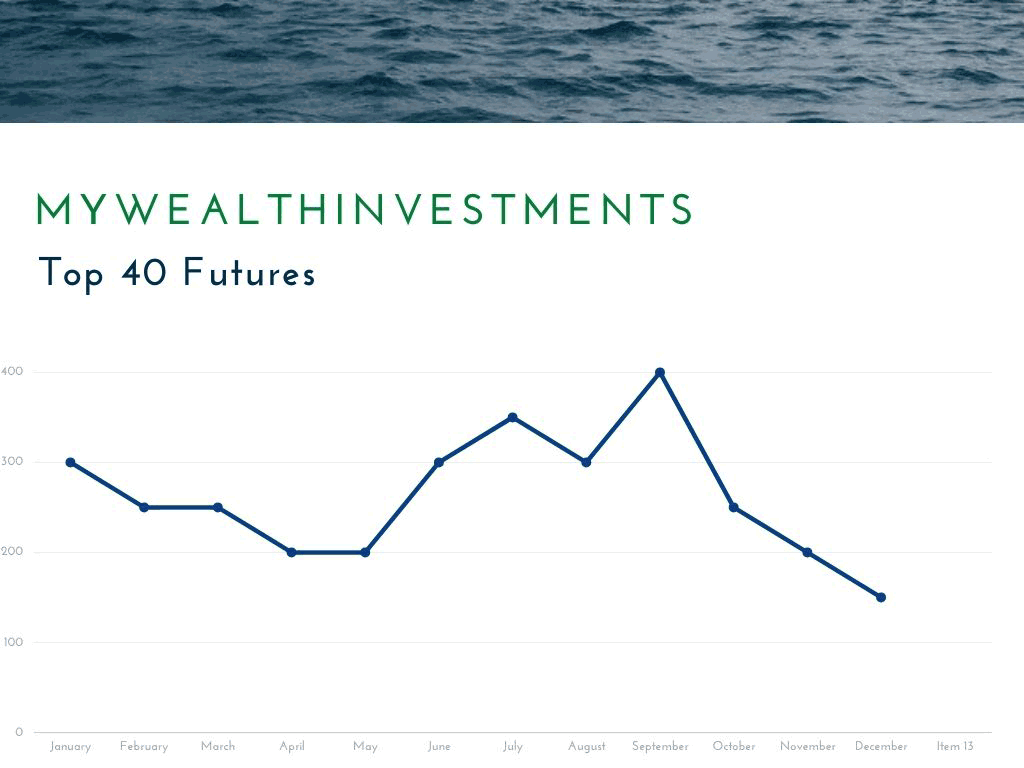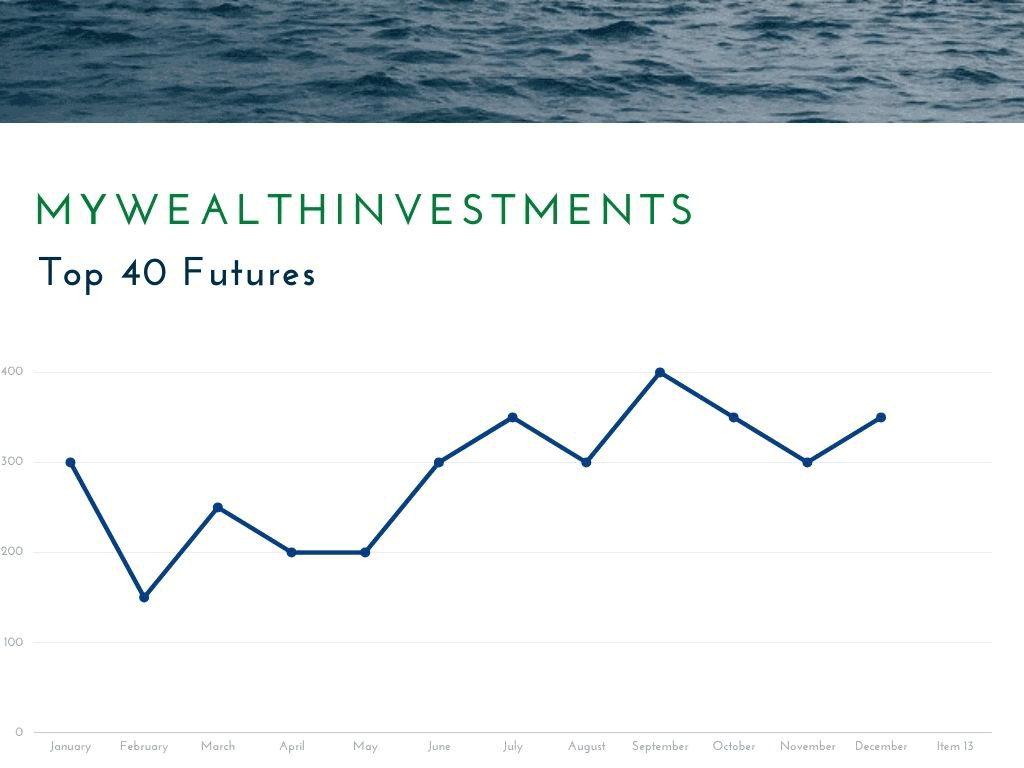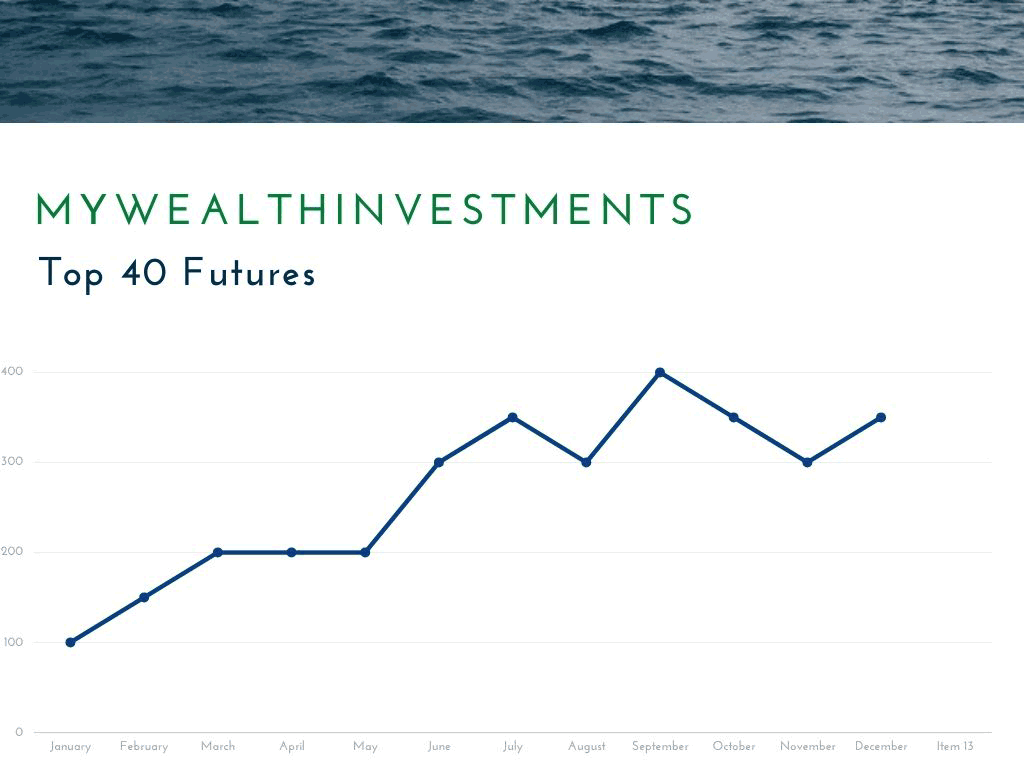
The Johannesburg Stock Exchange All-Share Index closed 1.03% lower at the 108 525 level.
Clicks Group reported a softer-than-expected set of full-year results for the year ended 31 August 2026, with HEPS of 1,422 cents, below the FactSet consensus of 1,485 cents. Revenue increased to R50.4 billion, while net income reached R3.3 billion, both slightly below market expectations. The result suggests that consumer spending pressures, particularly from higher fuel costs and interest rates, weighed on group performance. Despite the earnings miss, Clicks increased its shareholder payout, declaring a final dividend of 667 cents per share, up from 648 cents a year earlier. This brings the total dividend for the year to 925 cents per share, representing growth of 4.4% year-on-year. Management remains cautious on the outlook, warning that the retail environment is likely to stay highly competitive as consumers continue to face financial strain. Low product inflation is also expected to persist, although the group’s pharmaceutical distribution business, UPD, will benefit from a regulated medicine price increase effective from 1 October 2026. Looking ahead, Clicks plans to continue investing for growth, with capital expenditure of R1.5 billion planned for FY2027. The group intends opening 40 to 50 new stores, expanding specialised pharmacies and convenience formats, while increasing investments in technology, omnichannel capabilities and supply-chain infrastructure to support its long-term target of 1,200 stores.
In a trading update from CANAL+ SA, the group reported a 37.5% increase in revenue to €6.4 billion for the nine months ended 30 September 2026, primarily reflecting the acquisition of MultiChoice Group. On a like-for-like basis, however, revenue was broadly flat at-0.3%, indicating that most of the reported growth came from the enlarged group structure rather than underlying organic growth. The Africa and Asia division was the standout performer, with revenue more than tripling to €2.6 billion following the MultiChoice acquisition. Excluding MultiChoice, the region delivered 10.2% like-for-like revenue growth, supported by strong subscriber growth in French-speaking Africa, double-digit growth in CANAL+ Telecom Africa, and continued momentum in Asian markets. However, MultiChoice’s like-for-like revenue declined 3.0%, largely due to weaker subscription revenue in South Africa. The group’s content production business also performed strongly, with revenue increasing 9.3% to €530 million. This was driven by strong box-office performances from STUDIOCANAL, increased international sales, and the contribution from the acquisition of Lucky Red, reinforcing the importance of content production as a growth driver. Looking ahead, management said it remains on track to achieve its 2026 targets, including €250 million in Adjusted EBIT synergies, €220 million in free cash flow synergies, Adjusted EBIT of €735 million, and free cash flow above €250 million. The company also highlighted progress in the MultiChoice turnaround strategy and recently secured exclusive rights to all UEFA men’s club competitions across more than 40 African countries for the 2027-2031 period, strengthening its long-term sports content offering across the continent.
In a trading update from Pick n Pay Stores Limited for the 26 weeks ended 30 August 2026, The company said that it expects loss per share (EPS) to improve by between 40% and 50%, to between-40.52 cents and -33.77 cents, compared with a loss of -67.53 cents in the corresponding period last year.
Similarly, headline loss per share (HEPS) is expected to improve by between 25% and 35%, to between-44.83 cents and -38.85 cents, versus a headline loss of -59.77 cents per share in H1 FY26. Management noted that the percentage improvement appears large partly because the prior-period headline loss was relatively small in absolute terms. The group also announced the successful conclusion of negotiations with its primary labour union, SACCAWU, resulting in a labour agreement and the formal withdrawal of the Section 189A consultation process. This removes a key uncertainty for the business as management continues its turnaround efforts.
In a production update from Valterra Platinum Limited, the company reported a resilient third-quarter performance despite safety-related disruptions, with total PGM metal-in-concentrate (M&C) production declining 6% to 804,300 ounces. Own-mined production fell 5% to 511,900 ounces, largely due to safety stoppages at Amandelbult following a fatal incident, while purchased concentrate volumes declined 7%. A strong performance from Mototolo, where production increased 7%, helped offset weaker output from Mogalakwena, Amandelbult and Unki. The group’s refined production was significantly affected by the planned re-phasing of maintenance and stock counts into the third quarter. As a result, refined PGM production decreased 41% to 576,900 ounces, while PGM sales volumes fell 27% to 683,300 ounces. However, year-to-date refined production and sales volumes remained broadly in line with the prior year, indicating that the decline was primarily timing-related rather than operational. Commodity prices remained supportive, with the average realised PGM basket price increasing 15% in rand terms to R38,815 per ounce and 24% in US dollar terms to US$2,383 per ounce. Individual metal prices were notably stronger year-on-year, with platinum up 24%, palladium up 14%, rhodium up 38%, iridium up 80%, and ruthenium surging 98% during the quarter. The company maintained its 2026 guidance, expecting both M&C and refined production of between 3.0 million and 3.4 million ounces. Chrome production increased 7% to 277,000 tonnes, while year-to-date chrome production rose 41% and chrome sales increased 42%. Management expects cash operating costs to finish near the upper end of guidance due to inflationary pressures and safety-related disruptions but remains confident of achieving its targeted all-in sustaining cost of approximately US$1,050 per 3E ounce.
SA Economy:
September’s inflation data provided a welcome surprise, with headline inflation rising to 4.5% from 4.4%, below market expectations of 4.7%, reducing the likelihood of another interest rate hike at the South African Reserve Bank’s final MPC meeting of the year. Despite the relatively muted inflation outcome, transport costs surged 10.8% year-on-year, driven by a 46% increase in diesel prices and a 25% rise in petrol prices, highlighting the growing pressure that fuel costs are placing on consumers and businesses. Economists believe inflation pressures remain largely contained, with food inflation increasing only marginally to 1.2% from 1.1%, and little evidence so far that higher fuel prices are spreading more broadly through the economy. The challenge for the South African Reserve Bank is that inflation is expected to move above 5% later in 2026 and early 2027, while the repo rate already stands at 7.25% following increases in May and September. For now, the September inflation print supports the case for rates to remain unchanged
Global Economy:
Hong Kong’s annual inflation rate rose to 1.9% in September 2026 from 1.7% in August, above market expectations of 1.8%. This marked the highest reading in three months.
Hong Kong’s seasonally adjusted unemployment rate ticked up to 3.9% in the three months ending September 2026, from 3.8% in the previous period.
US initial jobless claims fell by 6 000 to 194 000 in the week ended October 17, below expectations and the lowest since mid-July, signalling labour market resilience. Continuing claims rose by 25 000 to 1.728 million in the week ended October 10.
Global Company:
The FTSE 100 closed 0.26% lower at 10 725. Mining shares were among the biggest drags on the index, with Antofagasta falling more than 6%, while Fresnillo and Anglo American each declined around 5.5%. Endeavour Mining also lost more than 4%, reflecting broad weakness across the resources sector. Banking stocks remained under pressure ahead of next week’s UK Budget, amid concerns that the government could introduce higher taxes on the sector. Standard Chartered dropped more than 4%, while Barclays fell over 2% after announcing plans to cut 5,000 jobs through AI-driven efficiencies and reporting weaker-than-expected bond trading performance for the third quarter. HSBC and Lloyds Banking Group also declined by more than 2%, while NatWest lost over 1%. Retailer J Sainsbury slipped more than 2% after reporting first-half like-for-like sales growth that fell short of market expectations.
Providing support to the market were defensive sectors such as healthcare and consumer staples. AstraZeneca and GSK both gained 2.6%, while Unilever rose 3.0% and British American Tobacco advanced more than 2.0%.
The Hang Seng Index is trading 0.62% higher at 23 803. Chinese AI startup DeepSeek had raised about US$15 billion offered a potential positive signal for the domestic AI sector, although it failed to offset broader market weakness. Notable laggards included SMIC (-0.13%), Genscript Biotech (-4.9%) and Lenovo (-1.8%). For the week, Hang Seng declined by more than 6%.
In China, the Shanghai Composite is down 0.44% at 3 642.
The Dow Jones Industrial Average closed 0.02% higher at 52 868, while the S&P 500 closed 1.22% lower at 7 663. The selloff was driven by growing concerns that major technology companies may need to significantly increase borrowing to fund their expanding artificial intelligence infrastructure investments. Meta Platforms plunged 7.0% despite reporting better-than-expected earnings and revenue, as its plans to increase capital expenditure revived worries about the rising costs associated with the AI race. Other large technology companies also moved lower ahead of their earnings releases next week. Amazon fell 4.6%, Alphabet lost 3.2%, and Microsoft declined 2.2%, reflecting investor caution toward the sector. The weakness extended across semiconductor stocks as the recent rotation out of chipmakers continued. AMD tumbled 8.1%, Intel fell 8.0%, Micron dropped 6.3%, and Nvidia lost 4.4%. Equipment manufacturer Lam Research was one of the biggest decliners, plunging 11.8% after issuing weaker-than-expected guidance. Tesla also came under pressure, falling 3.1% after scaling back its spending plans, with quarterly capital investment coming in below market expectations.
Commodities:
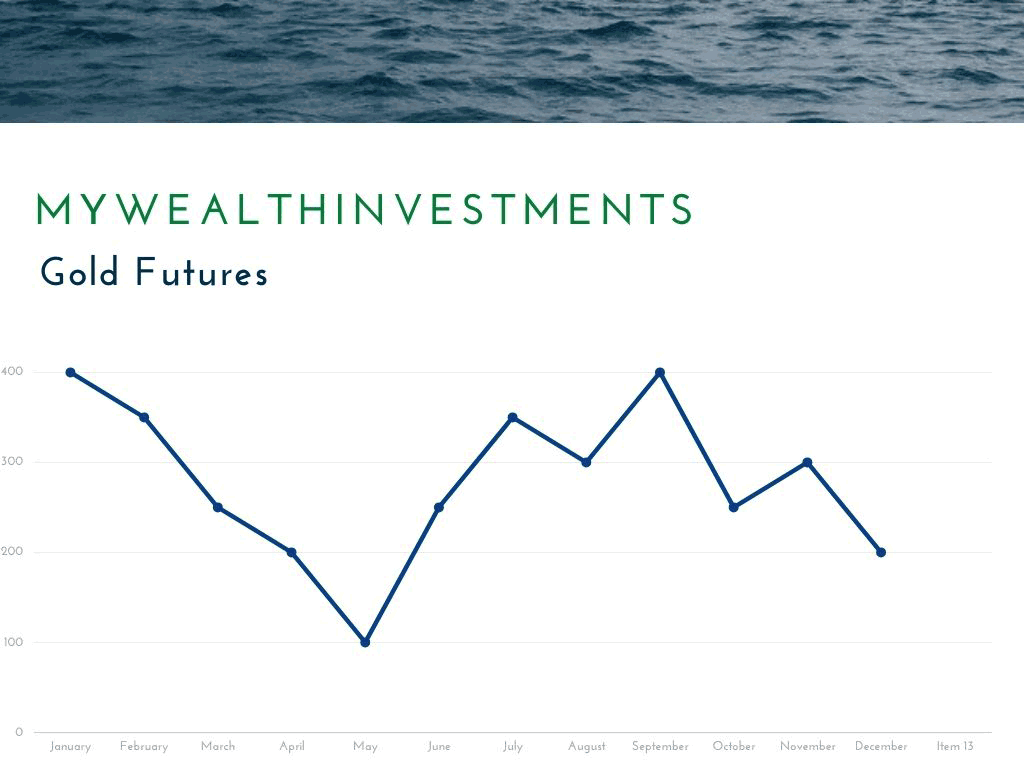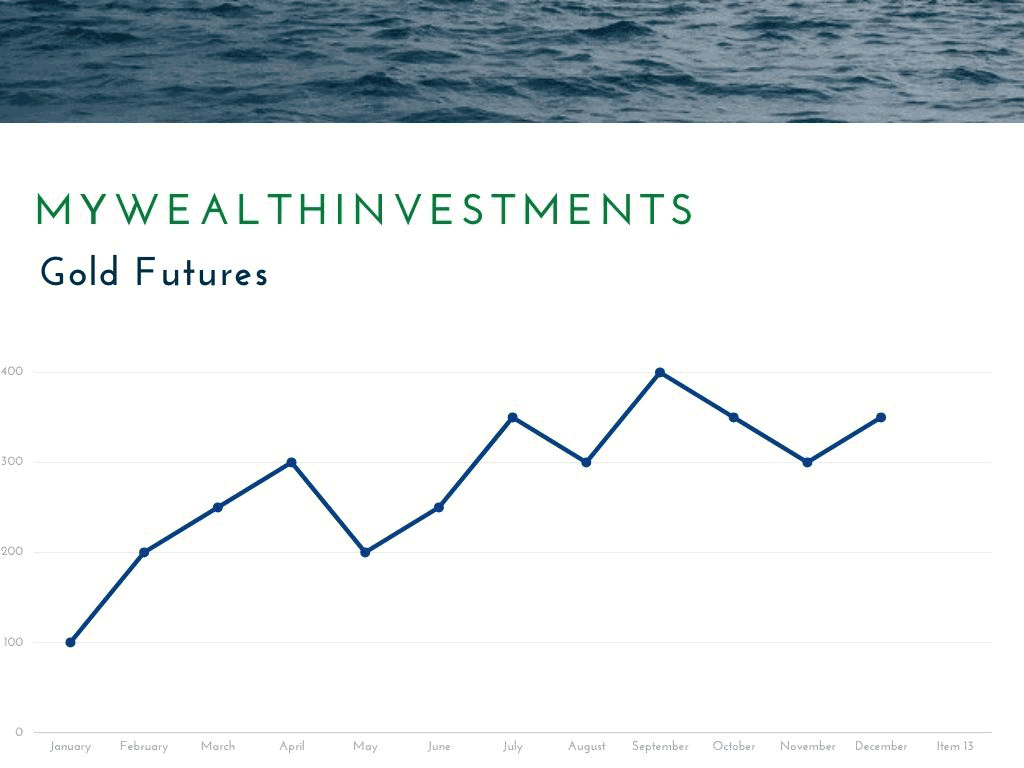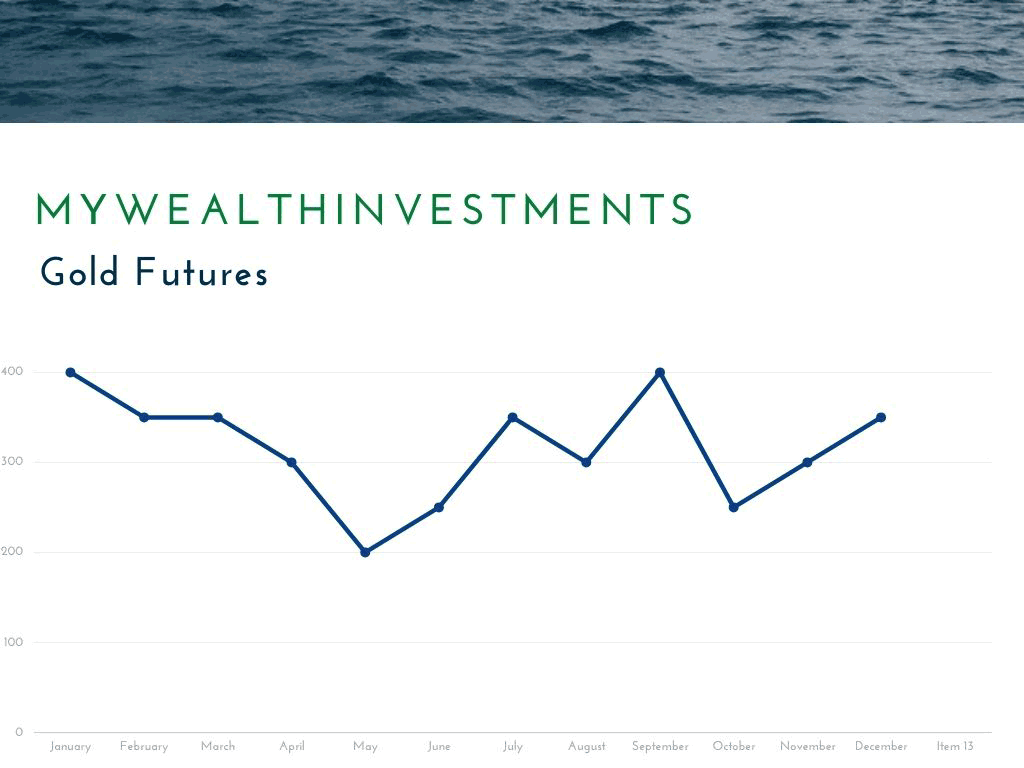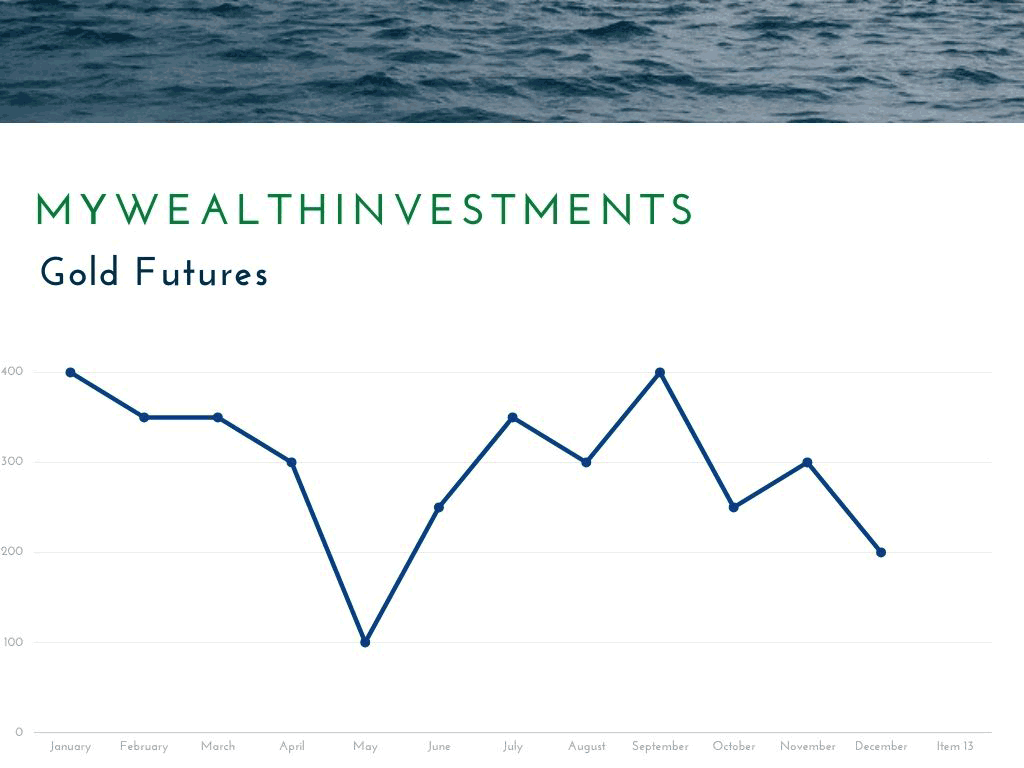
Gold is trading lower by 1.81% at $4 015/oz, while Platinum is lower by 1.26% to $1 572.85/oz.
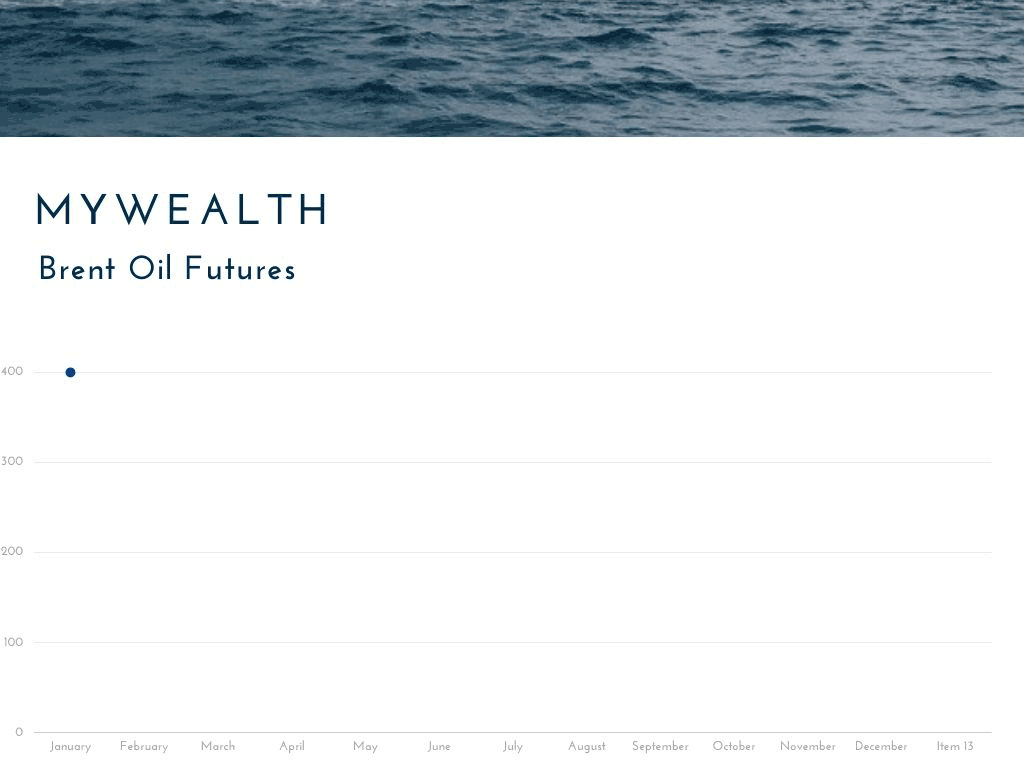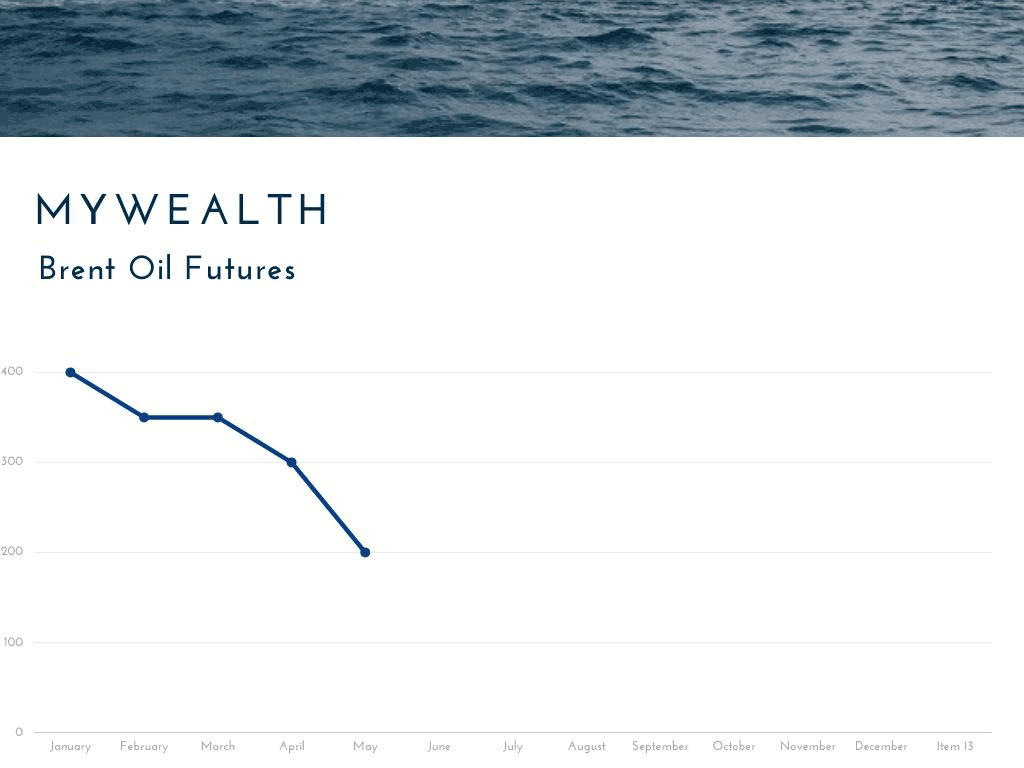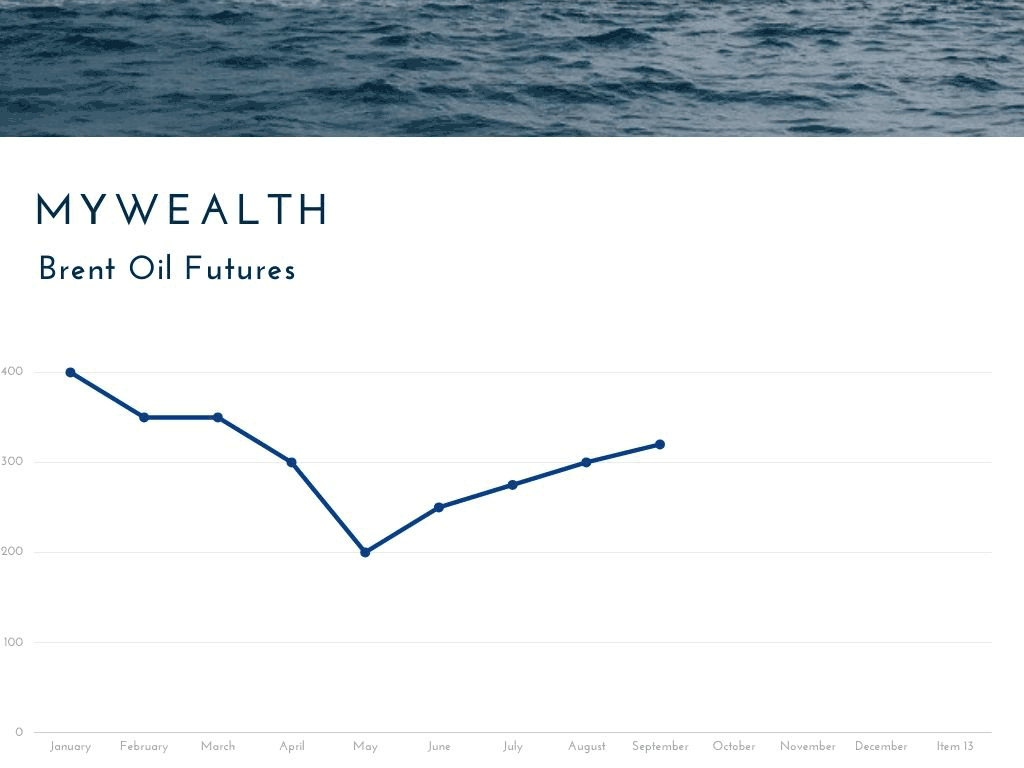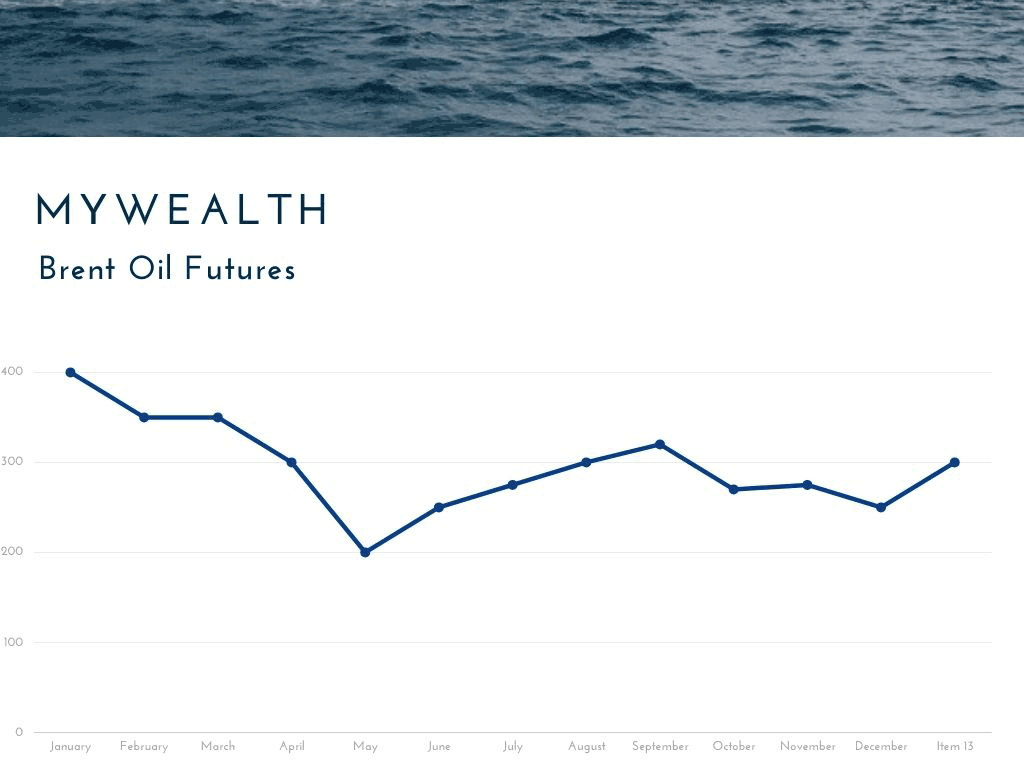
Brent crude was 2.46% higher at $113.95.
Currency:
The rand traded at R16.51 against the US Dollar, R22.11 against British Pound and R18.51 against the Euro.
The Euro is slightly weaker against the US Dollar to trade at $1.1211.
 .
| Market Indicators | |||||||
| Commodities $ | Cross Currencies ($) | Major Indices | |||||
| Gold | 4015.45 | -1.81% | USD/ZAR | 16.51 | Top40 | 100543.39 | -1.19% |
| Platinum | 1572.85 | -1.26% | GBP/ZAR | 22.11 | Dow 30 | 52867.98 | 0.02% |
| Brent | 113.95 | 2.46% | EUR/ZAR | 18.51 | S&P 500 | 7663.43 | -1.22% |
| Copper | 6.44 | -0.62% | EUR/USD | 1.1211 | FTSE | 10725.03 | -0.26% |
| Palladium | 1055.67 | -0.58% | USD/JPY | 156.90 | DAX | 25371.75 | -1.08% |
| Iron Ore | 90.60 | 0.61% | BITCOIN | 81666.70 | Shanghai | 3641.88 | -0.44% |
| Source: FACTSET | |||||||